A share sale is the usual way to bring in a new owner or exit a Thai private limited company. The mechanics are simple, but a defect in the transfer document can make the sale void, and the tax result depends on who the seller is. This article sets out the steps and the taxes that apply.
1. The Procedure
- Check the articles and any shareholders’ agreement. Under Section 1129 of the Civil and Commercial Code (CCC), shares can be transferred without the company’s consent unless the articles of association provide otherwise for registered shares. Many private companies restrict transfers through director approval or pre-emption rights, so confirm this first. If the buyer is foreign, check the position under the Foreign Business Act, and note that the company must continue to have at least two shareholders.
- Agree the commercial terms. Record price, payment timing, warranties and conditions in a share purchase agreement. Keep evidence of the seller’s original investment, because tax is calculated on the gain.
- Sign a valid transfer instrument. CCC s.1129 requires the transfer of registered shares to be in writing, signed by both transferor and transferee, with at least one witness who signs to attest the signatures, and the instrument must state the share numbers. Otherwise the transfer is void. The Supreme Court applies this strictly, where the transfer was void because no witness attested the signatures. A signed purchase agreement alone is not safe.
- Pay stamp duty. The transfer instrument is dutiable under Item 2 of the stamp duty schedule (Revenue Code s.104) at THB 1 for every THB 1,000 or part thereof, calculated on the higher of the paid-up value of the shares or the price stated in the instrument
- Register the transfer. Record the transferee’s name and address and the relevant dates in the share register (CCC ss.1138 and 1139). Under s.1129, the transfer cannot be relied on against the company or third parties until it is entered in the register. The directors must also send the shareholder list to the Registrar at least once a year, no later than the fourteenth day after the annual ordinary meeting (CCC s.1139).
2. Tax On The Sale
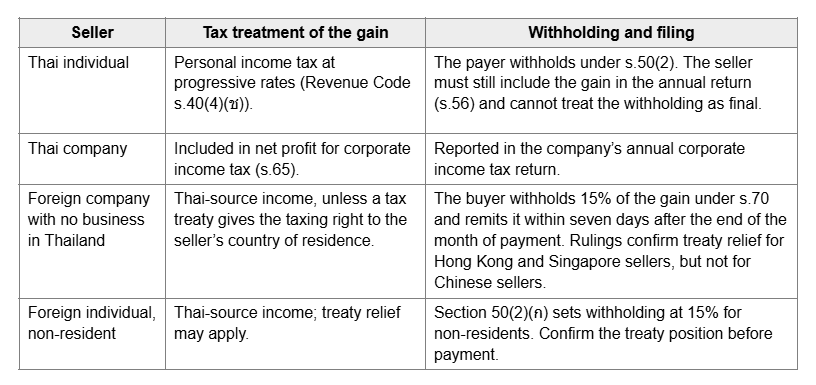
Only the gain is taxed. The benefit from a transfer of shares is assessable income under Revenue Code s.40(4)(ช) only to the extent it exceeds the amount invested. A sale at or below cost produces no assessable income for the seller. The treatment depends on the seller:
• No specific business tax. Specific business tax applies only to sales of shares on the Stock Exchange of Thailand (Revenue Code s.91/2(7)), so an off-market sale of private company shares is outside it.
• Price below fair value. If shares are sold below market value without good reason, the assessing officer may assess the consideration at market value. For unlisted shares, the Revenue Department has accepted net asset value per share from the latest audited accounts as a reasonable price.
• Practical point. Fix the price, stamp duty allocation and withholding treatment in the agreement, and close with the signed instrument, tax certificate and updated register delivered together.
Disclaimer
This article is provided for general information only and does not constitute legal or tax advice. Reading it does not create a lawyer-client relationship. The law, Revenue Department practice and tax treaty positions change, and the right approach depends on the facts of each transaction. Please obtain advice from a qualified lawyer or tax adviser before acting on any part of it.
Call 020556212
Email : contact@w-lawthai.com
Line @wlaw
W Law and Real Estate International (Thailand) Co., Ltd.
- Bangkok Office: 518/3 4th Floor, Maneeya Center North Building, Ploenchit Road, Lumpini, Pathumwan, Bangkok Metropolis 10330
- Phuket Office: 63/202 Moo 2 Royal Phuket Marina, Thepkasattri Road, Kohkaew, Muang Phuket, Phuket Province 83000
- Pattaya Office: 666/66 Level 3 Conventional Hall Brighton Grand Hotel Pattaya, Moo 5, Naklua, Banglamung, Chonburi Province 20150
